
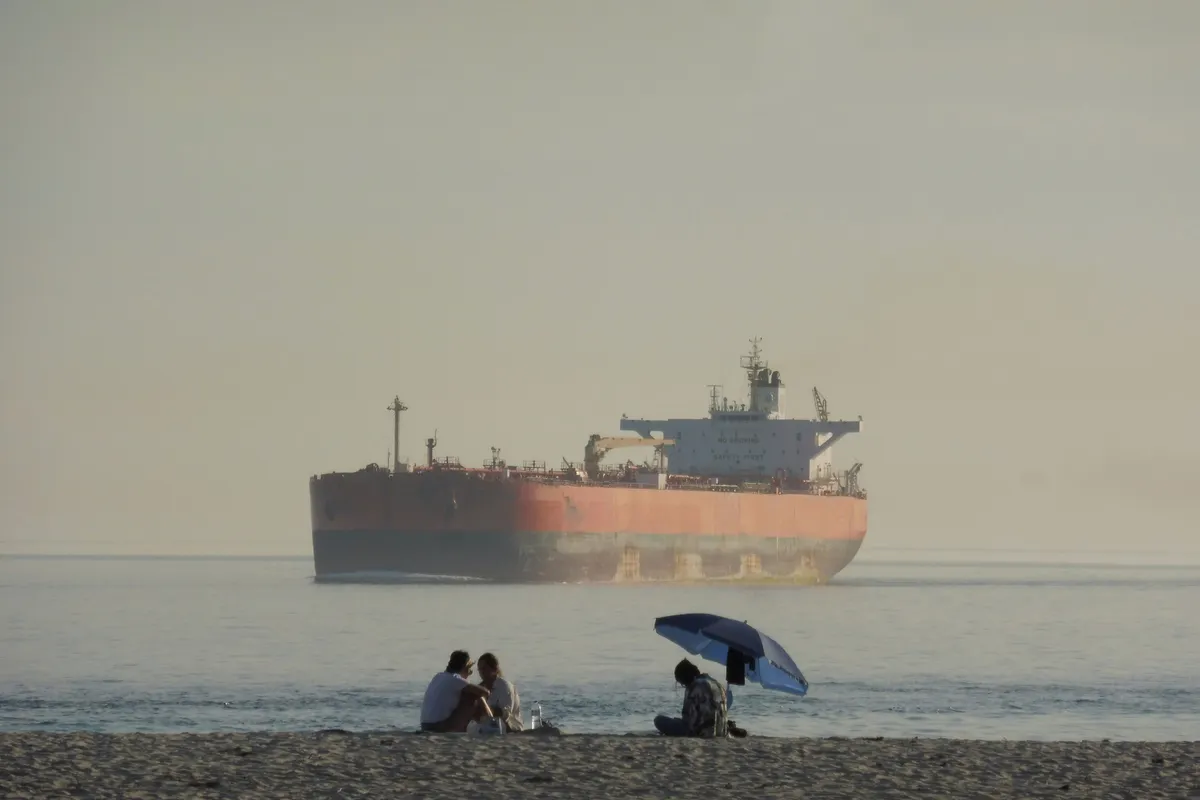
US Energy Secretary Chris Wright’s White House oil shipments claim that more crude left the Middle East on Monday than before the Iran conflict began has been challenged by an independent analyst, who says the figure appears to combine volumes across multiple days.
Wright told reporters that more than 17 million barrels flowed through the Strait of Hormuz alone on Monday, and that when bypass pipelines were added, total exports exceeded pre-conflict levels.
White House oil shipments claim queried over ‘mathemagics’
Samir Madani, co-founder of TankerTrackers.com, described the calculation as ‘mathemagics’, telling Fortune that on Monday, 31 August, only an estimated 9.14 million barrels of oil exited the Arabian Sea across all routes, including Hormuz and alternatives.
For context, prewar regional exports across all routes ran at roughly 23.3 million barrels per day, according to Drop Site News on X. Monday’s estimated figure was well below that baseline.
Madani’s account helps explain why Brent crude has remained above $95 per barrel.
Labour market signals and bond market nerves
Vanguard‘s 401(k) database, covering 5 million workers at 2,500 companies, ‘shows near-zero employment growth in August’, according to Senior Economist Adam Schickling.
Schickling said the flat hiring data coincides with a large number of workers dropping out of the labour force entirely. The 25-to-54-year-old labour force participation rate has fallen roughly 50 basis points year to date, one of the largest non-recessionary drops on record, he said.
‘If prime-age participation had not fallen, we estimate that the current unemployment rate would be 4.4%,’ Schickling wrote, compared with its current level of 4.1%.
He added that he expects many of those dropouts to return to job-seeking in coming months, ‘creating upward pressure on the unemployment rate as these workers re-enter the labour force faster than they find jobs.’
In bond markets, the yield on the 30-year US Treasury eased to 5.25%, below a recent peak of 5.31%. The 10-year stood at 4.78%.
Jim Reid, global head of macro research at Deutsche Bank, pushed back on the view that a $40 trillion US debt pile is driving yields higher. ‘My view is that the latest rise in global yields is a continuation of the normalization after the financial repression of the 2010s, rather than a sign that markets are yet focused on fiscal concerns,’ he said.
His Deutsche Bank colleague George Saravelos noted that, for the first time outside the Great Financial Crisis, equity inflows into the US have overtaken fixed income, driven by what he called a booming American private balance sheet underpinned by AI and record profit margins.
Markets steady; Apple foldable price estimated at up to $2,500
Stock markets moved modestly higher. The S&P 500 rose 0.46% on Wednesday, with futures pointing to further gains. In Europe, the Stoxx 600 added 0.28% in early trading and the FTSE 100 was up 0.12%. Bitcoin stood at $77,865.
Analysts at J.P. Morgan estimate Apple’s forthcoming foldable iPhone Ultra will be priced at $2,000 to $2,500, making it the company’s most expensive handset. Analyst Samik Chatterjee and colleagues expect sales of fewer than 10 million units at launch.
Vanguard’s Schickling is now watching September’s jobs data for confirmation of whether the labour force is beginning to recover, the next official reading will offer the clearest test of his forecast.
